Nvidia Reports $96.2B Q2; Rubin Forecast at One-Fifth of Q3 Data Center Revenue
Nvidia reported fiscal Q2 2027 revenue of $96.221 billion, up 106% year over year. It guided Q3 to $108 billion ±2%, excluding China data-center compute, and forecast Vera Rubin at about 20% of Q3 Data Center revenue. Management also projected roughly 70% FY28 growth.

Nvidia’s $96.2 billion quarter comes with a $108 billion next-quarter revenue outlook. Management expects Vera Rubin to account for about 20% of Data Center revenue in Q3; that is a forecast, not the reported Q2 mix.
NVIDIA posted fiscal Q2 2027 (ended July): revenue $96.221 billion (+18% Q/Q, +106% Y/Y). Data Center $89.0 billion (+117% Y/Y). GAAP net income $59.688 billion / $2.46 per share; non-GAAP EPS $2.22; gross margin 75.0%. Q3 outlook $108.0 billion ±2%, with no China Data Center compute. On the call, Colette Kress pointed to ~70% FY28 revenue growth and a supply bottleneck through at least the end of fiscal 2028. Vera Rubin was forecast to represent ~one-fifth of Data Center revenue in Q3. Edge Computing $7.2 billion. Buybacks plus dividends ~$26 billion; $99 billion remaining authorization. Jensen Huang: “AI has reached its inflection point… Now, compute is revenue.”
The print#
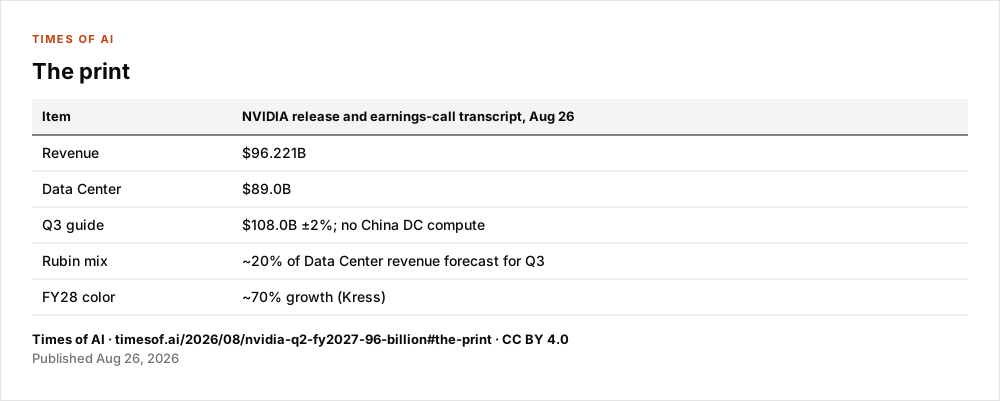
| Item | NVIDIA release and earnings-call transcript, Aug 26 |
|---|---|
| Revenue | $96.221B |
| Data Center | $89.0B |
| Q3 guide | $108.0B ±2%; no China DC compute |
| Rubin mix | ~20% of Data Center revenue forecast for Q3 |
| FY28 color | ~70% growth (Kress) |
The same-day AWS +2 million GPUs announcement is a separate infrastructure development.
Limits#
- 70% FY28 growth is a forward-looking management expectation on the call, not a reported result.
- Whether that number survives a Rubin yield miss is open.
- $99 billion remaining buyback authorization is capacity, not a spend schedule.
Correction (October 14, 2026): The earnings-call transcript places Rubin’s approximately 20% Data Center share in the Q3 outlook, not Q2 results. Corrected all headline and summary fields, clarified China exclusion as an outlook assumption and removed the unverified Street comparison.